Bangalore Warehousing Market 2026: How It Grew, What Rents Say, What Comes Next
By Nihas MKH · Updated
In short
Bangalore had 57.0 million sq ft of Grade A warehousing and 11.8% vacancy at the end of 2025 (CRE Matrix). Transacted rents averaged Rs 25.6 per sq ft per month in Q1 2026 (Knight Frank), and WareOnGo's median asking rent for 20,000 sq ft-plus units is Rs 25. Belt medians run from Rs 22 on Tumkur Road to Rs 40 at the airport.
Bangalore (Bengaluru) closed 2025 with 57.0 million sq ft of Grade A warehousing and 11.8% vacancy, the loosest of India's big markets alongside Ahmedabad (CRE Matrix with CREDAI, CY'25). Transacted rents averaged Rs 25.6 per sq ft per month in Q1 2026, up 5% on a year earlier (Knight Frank, Q1 2026). On WareOnGo's own listings, the median asking rent for units of 20,000 sq ft and above is Rs 25, across 218 listings, as of September 2026. Read together, those numbers say one thing: supply has run slightly ahead of demand, so occupiers have leverage, but not evenly across the city.
This piece covers how the market got its shape, what rents are across its belts today, and what those rents are actually telling you.
How Bangalore's Warehousing Map Formed
Bangalore never had one warehousing corridor, because demand never came from one direction. It spread out along the highways, each belt serving a different destination.
- Northwest, NH-48 (Tumkur Road, Nelamangala, Dobbaspet): the Mumbai and Pune line, and home to the city's largest boxes.
- South, NH-44 (Hosur Road, Bommasandra, Jigani, Attibele): runs into the Tamil Nadu manufacturing belt around Hosur.
- East, NH-75 (Old Madras Road, Hoskote, Soukya Road): faces Chennai and its port.
- North (Devanahalli): follows the airport.
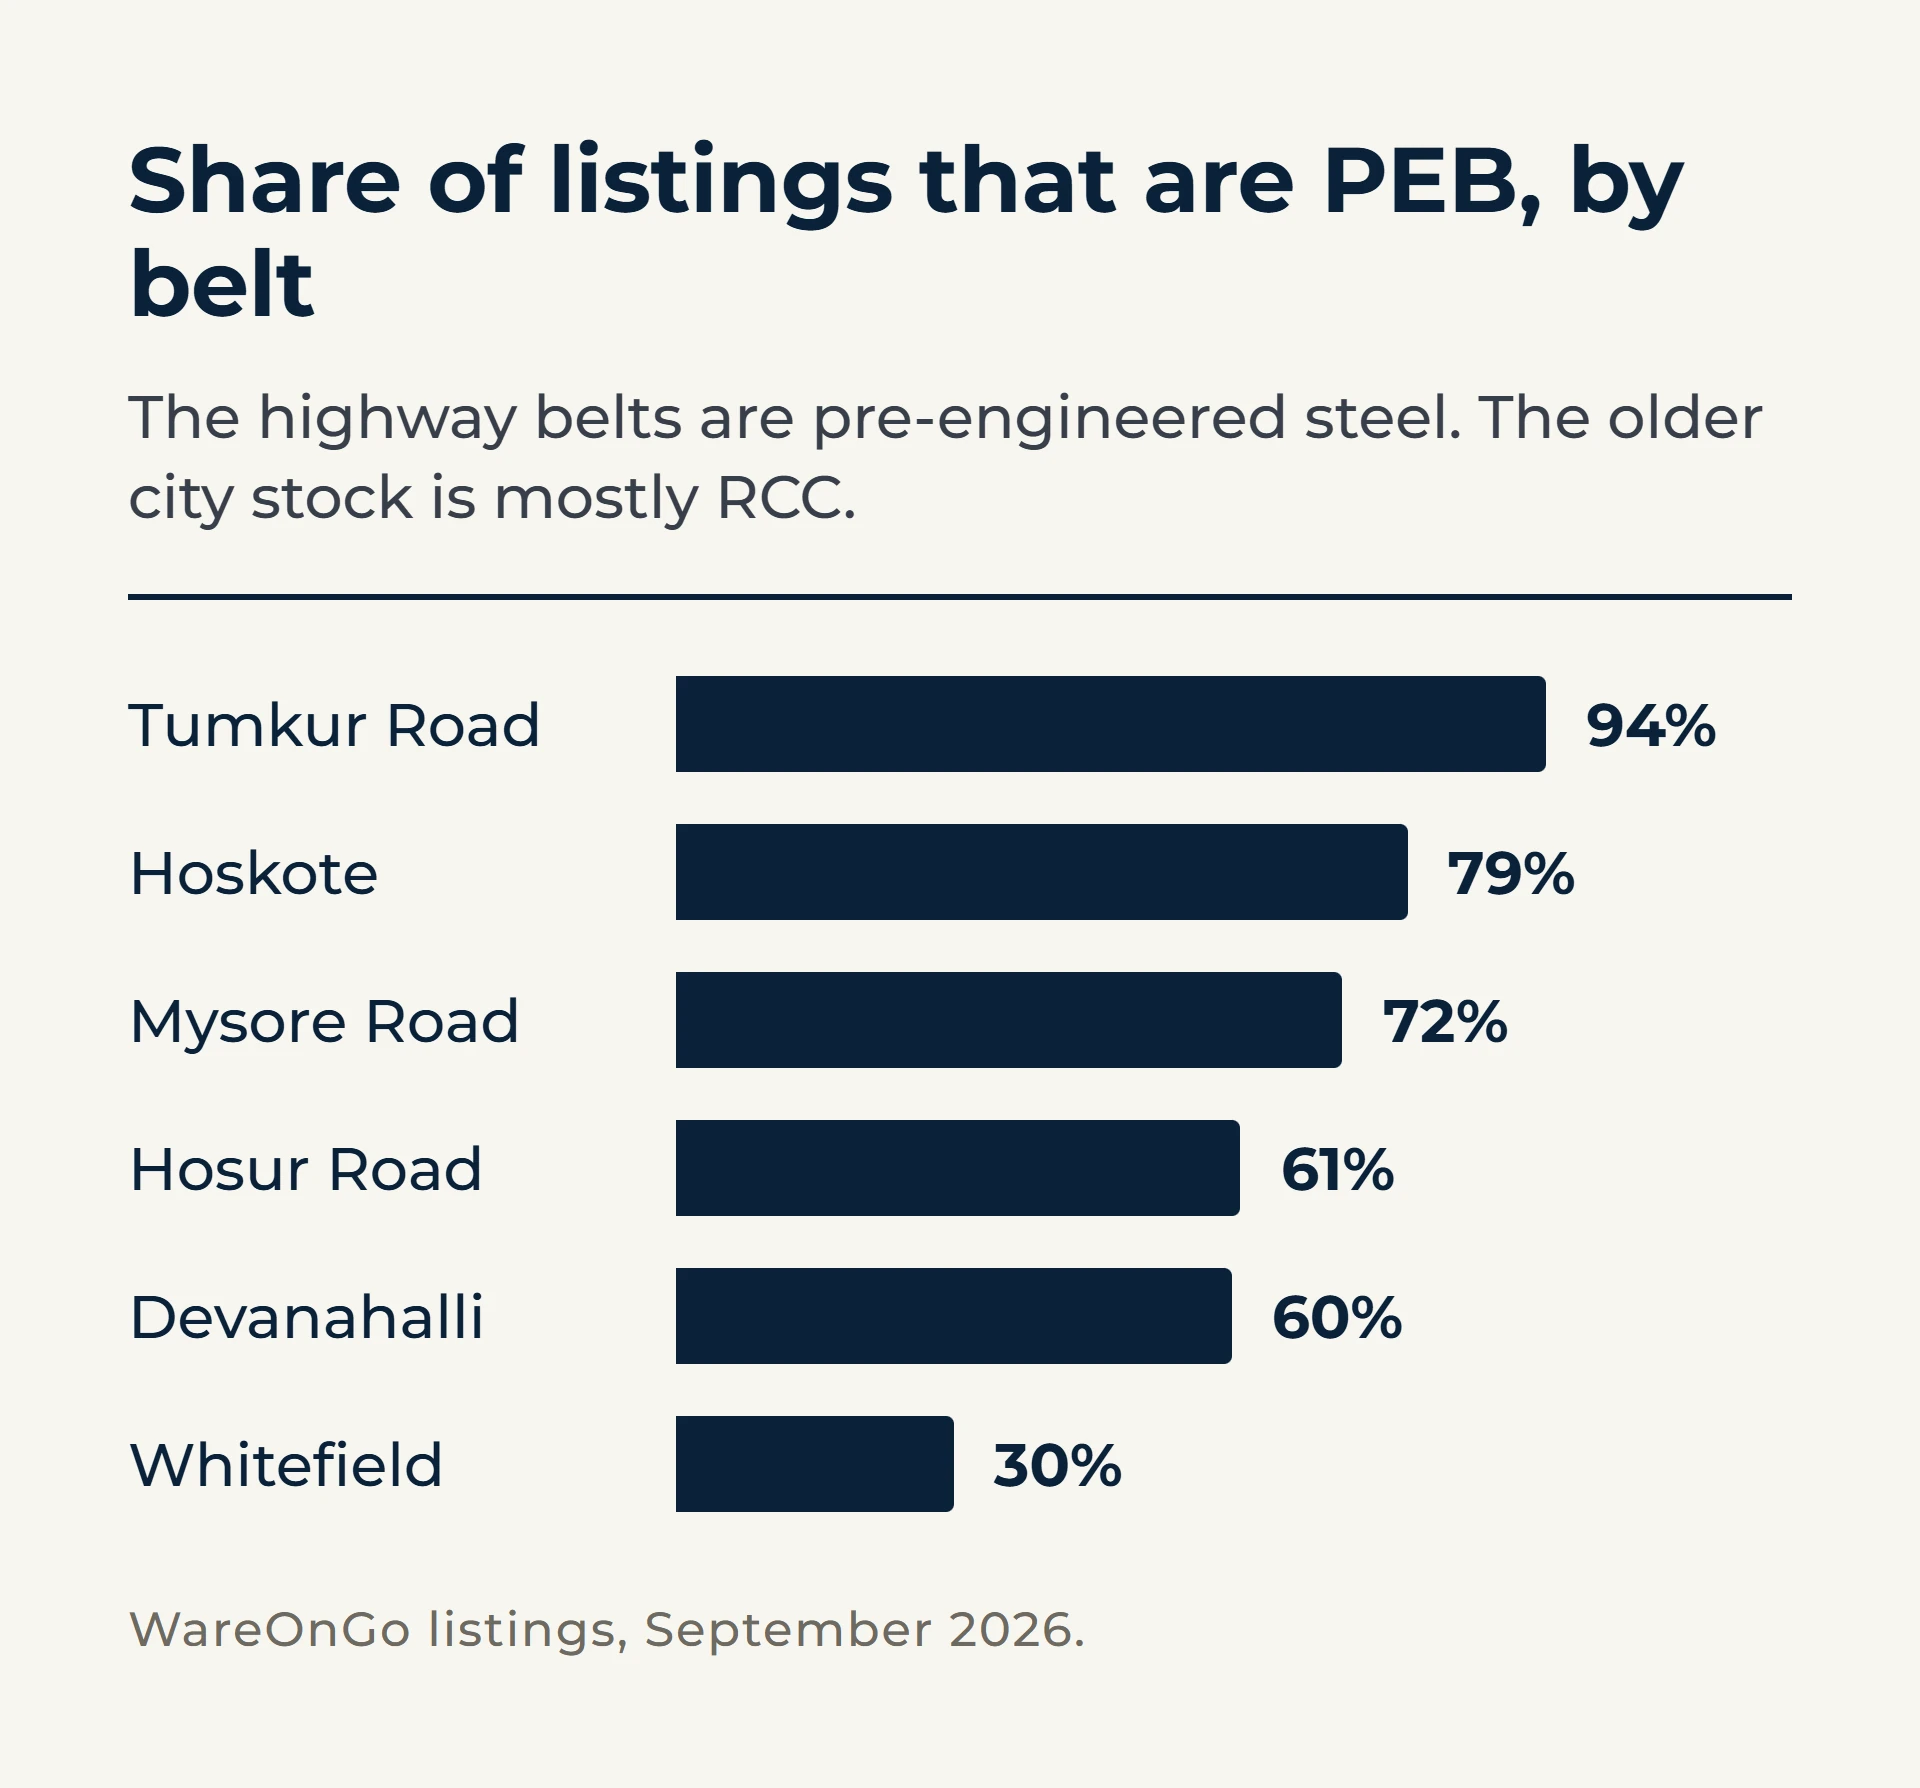
The evolution is written into the buildings themselves. Peenya, inside the city, is the older industrial stock: 60% of the warehouse listings we track there are RCC, with a median clear height of 13.5 ft and a median unit of 7,000 sq ft. Out on Tumkur Road, 94% of listings are pre-engineered steel (PEB), with a median clear height of 35.5 ft, a median unit of 45,000 sq ft and five docks. The market moved from converted godowns in the city to purpose-built sheds on the highways, and the specification jumped with it.
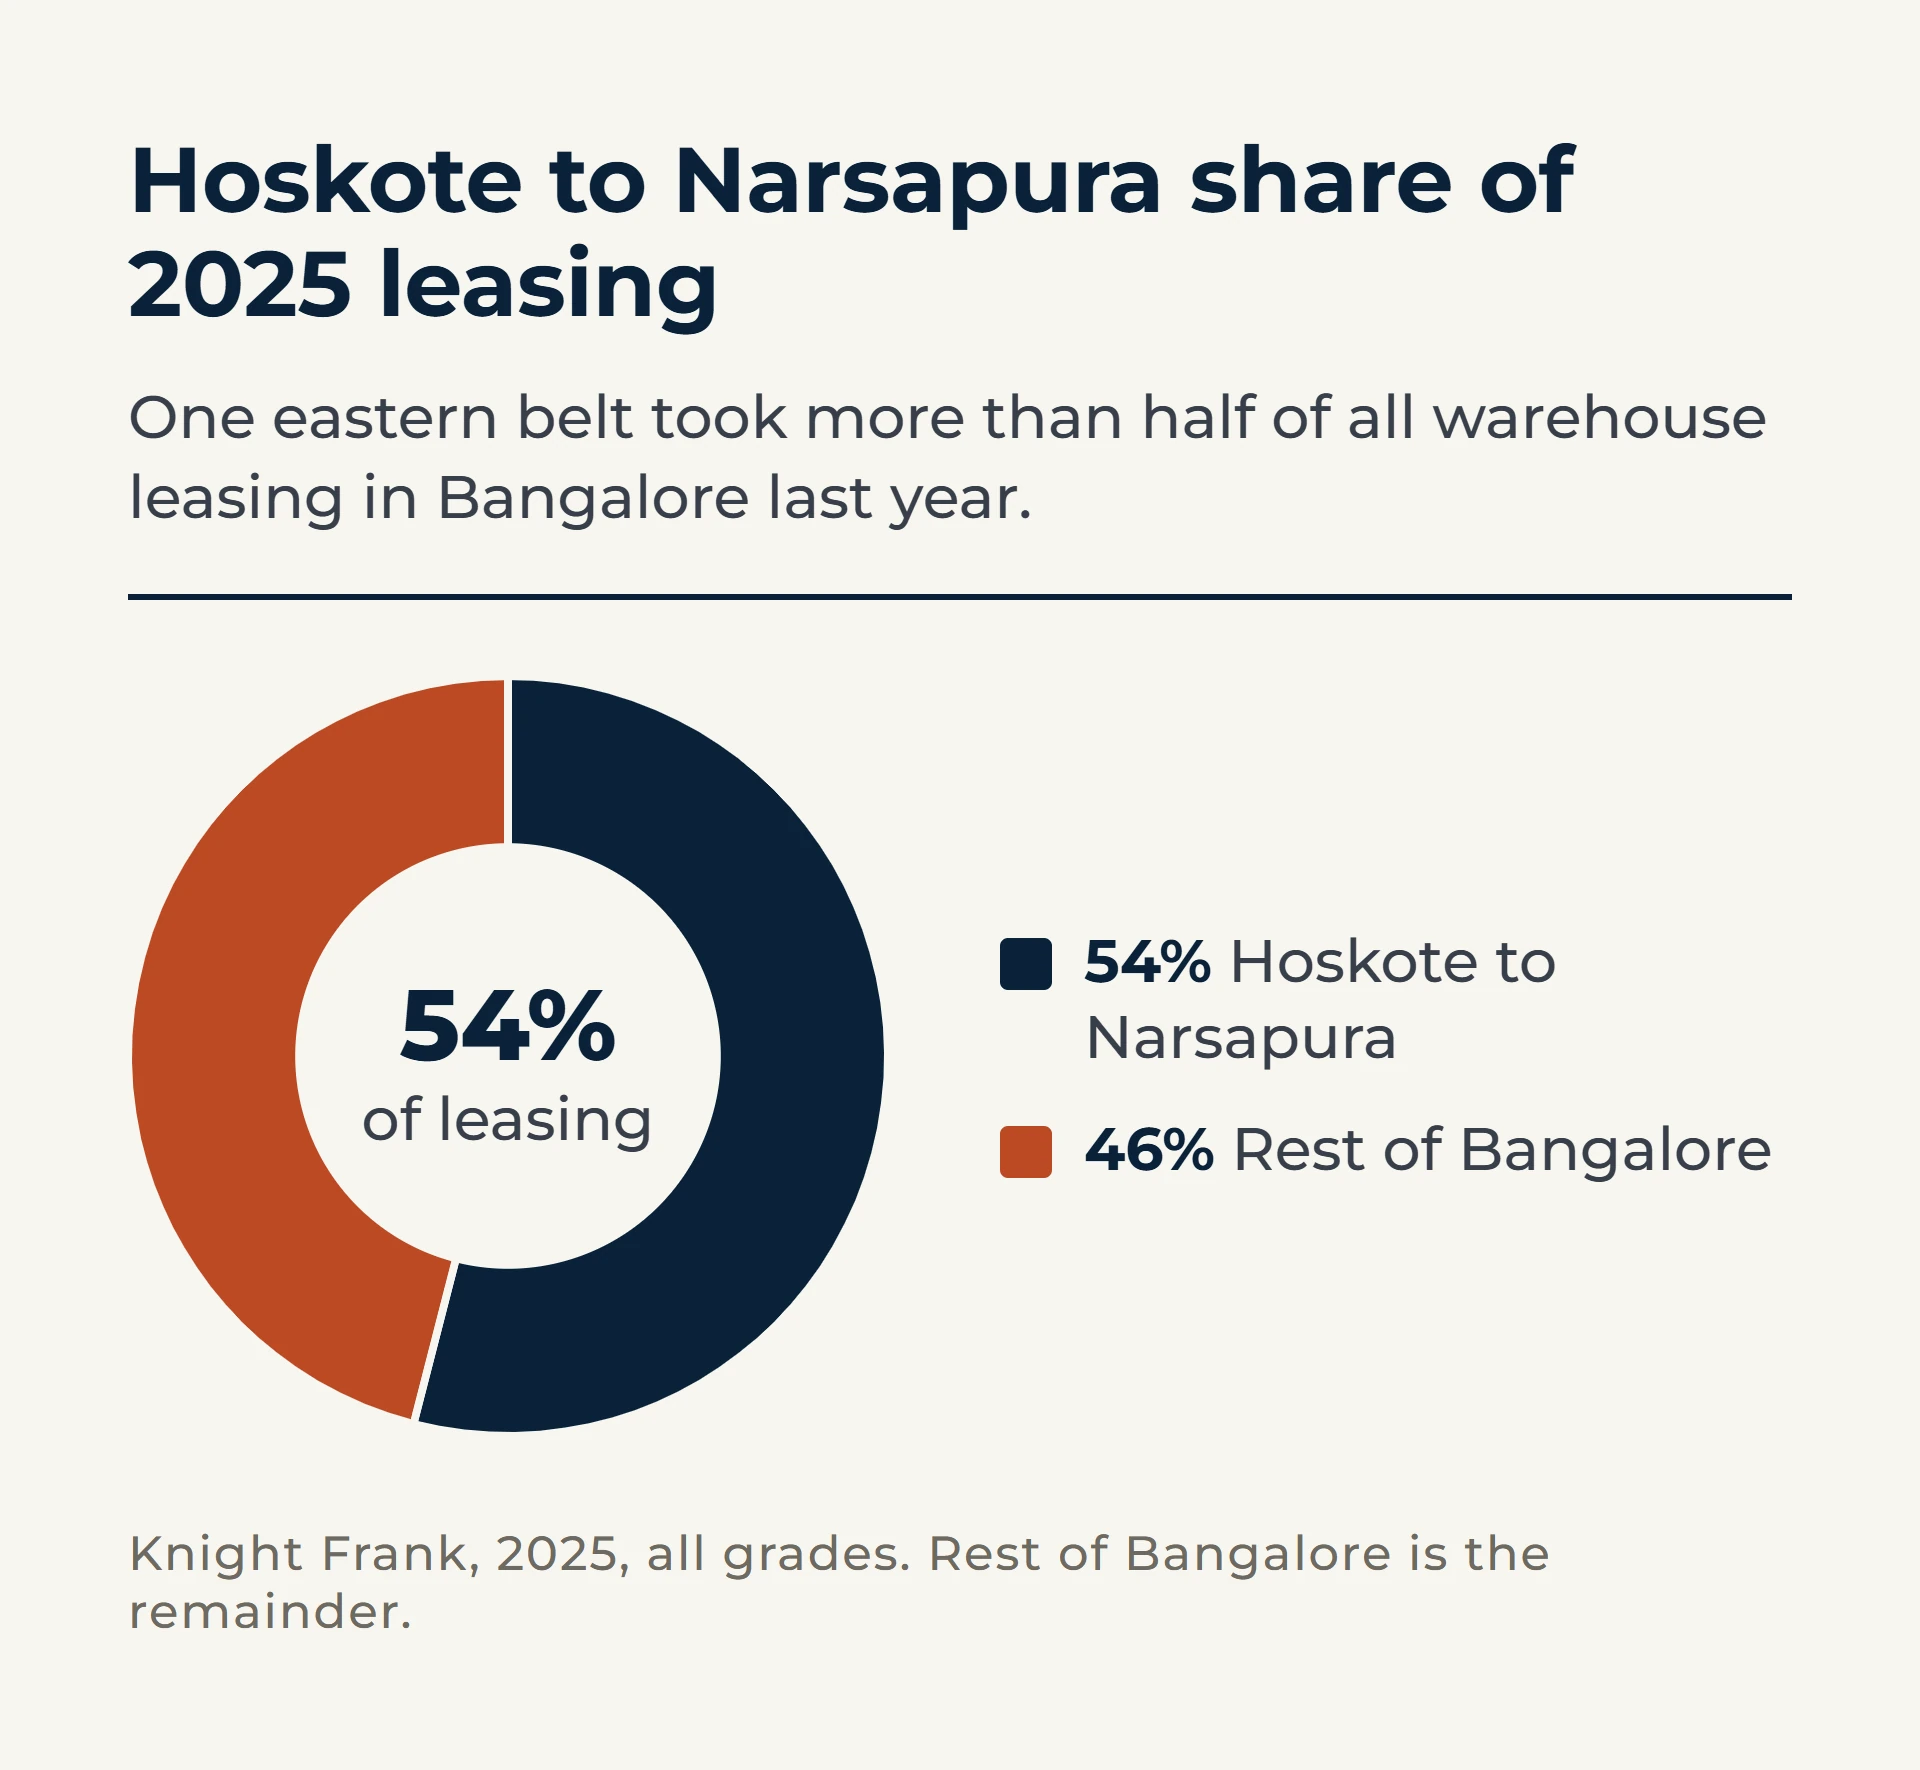
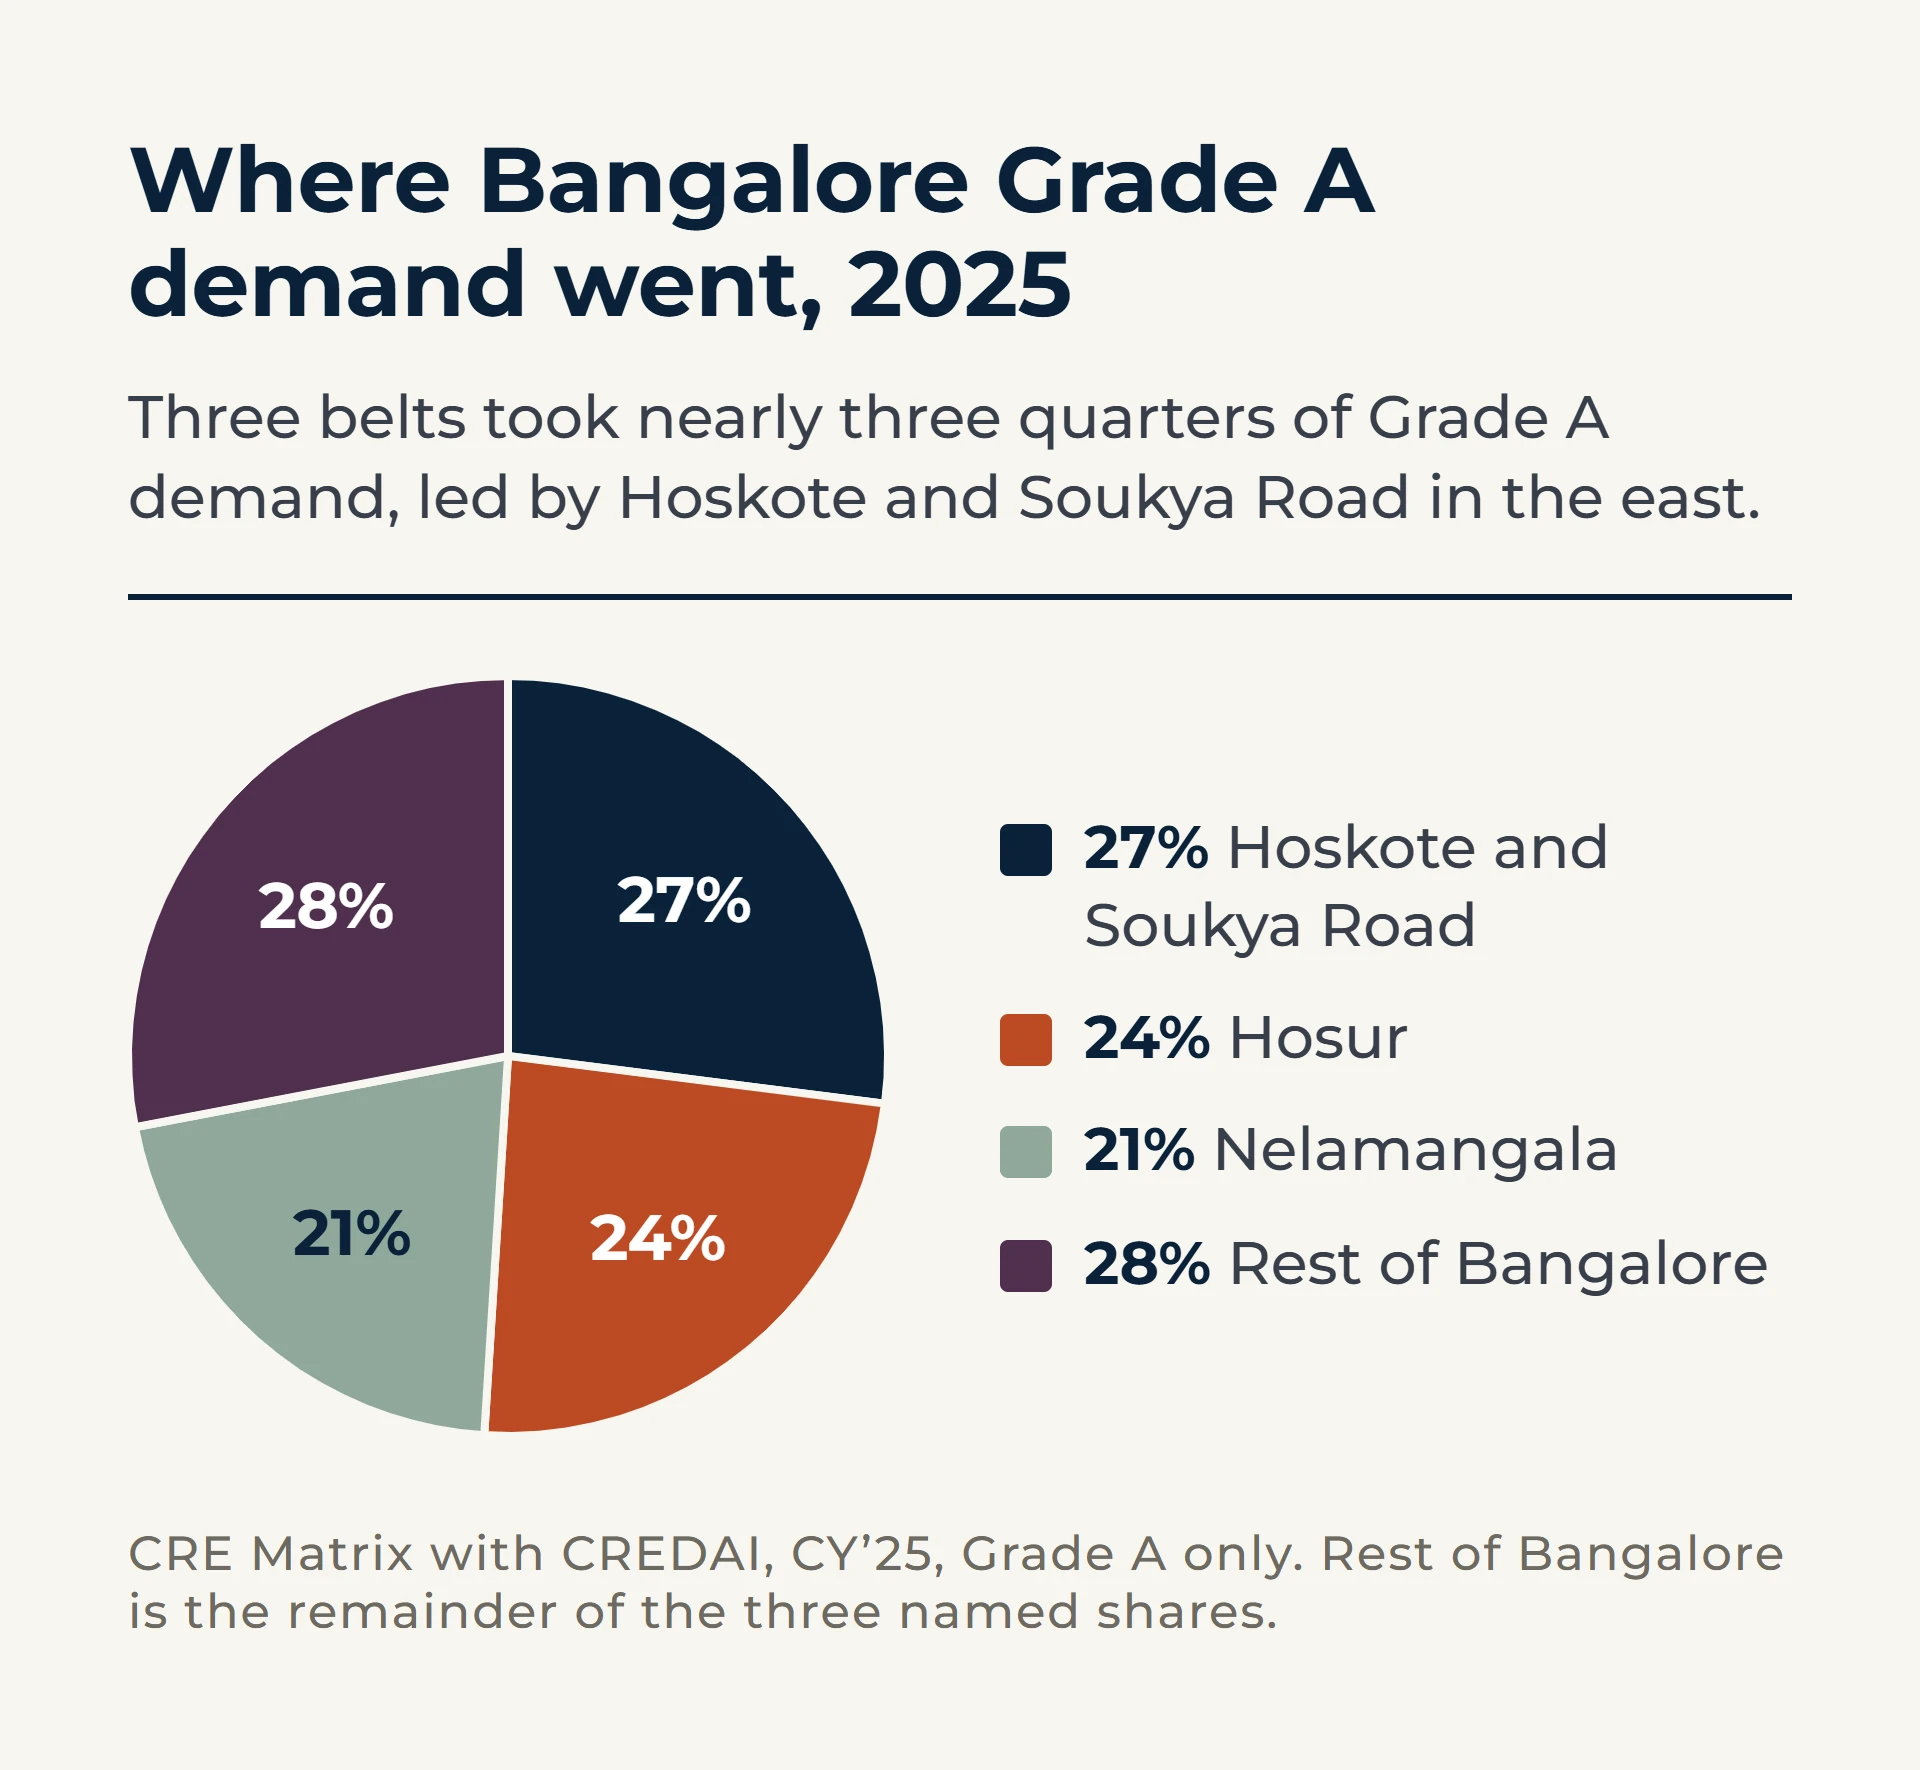
The centre of gravity keeps shifting. In 2025, the Hoskote to Narsapura belt took 54% of all Bangalore leasing by Knight Frank's count, while Attibele and Bommasandra fell from 17% to 6%. CRE Matrix, which counts Grade A only, puts CY'25 demand at 27% for Hoskote and Soukya Road, 24% for Hosur and 21% for Nelamangala. The two firms define their clusters differently, so the shares do not match, but both point east and northwest.
The Market in Numbers
| Measure | Figure | Source |
|---|---|---|
| Grade A stock, end 2025 | 57.0 million sq ft | CRE Matrix with CREDAI, CY'25 |
| Grade A demand / new supply, 2025 | 10.8 / 9.3 million sq ft | CRE Matrix with CREDAI, CY'25 |
| Grade A vacancy, end 2025 | 11.8% | CRE Matrix with CREDAI, CY'25 |
| All-grade leasing, 2025 | 8.2 million sq ft, up 24% | Knight Frank, 2025 |
| All-grade leasing, Q1 2026 | 1.8 million sq ft, up 27% | Knight Frank, Q1 2026 |
| Average transacted rent, Q1 2026 | Rs 25.6 per sq ft per month, up 5% | Knight Frank, Q1 2026 |
| Grade A share of total stock | 51% | Knight Frank, Q1 2026 |
Knight Frank's 2025 report puts Bangalore's all-grade vacancy higher still, at 19.1%, the highest of the eight cities it tracks. The difference from CRE Matrix's 11.8% is methodology: one counts Grade A only, the other counts Grade A and B. Either way, Bangalore is a tenant's market by national standards. Chennai, for comparison, sits at 4.7% Grade A vacancy.
What Warehouse Rents Are across Bangalore's Belts
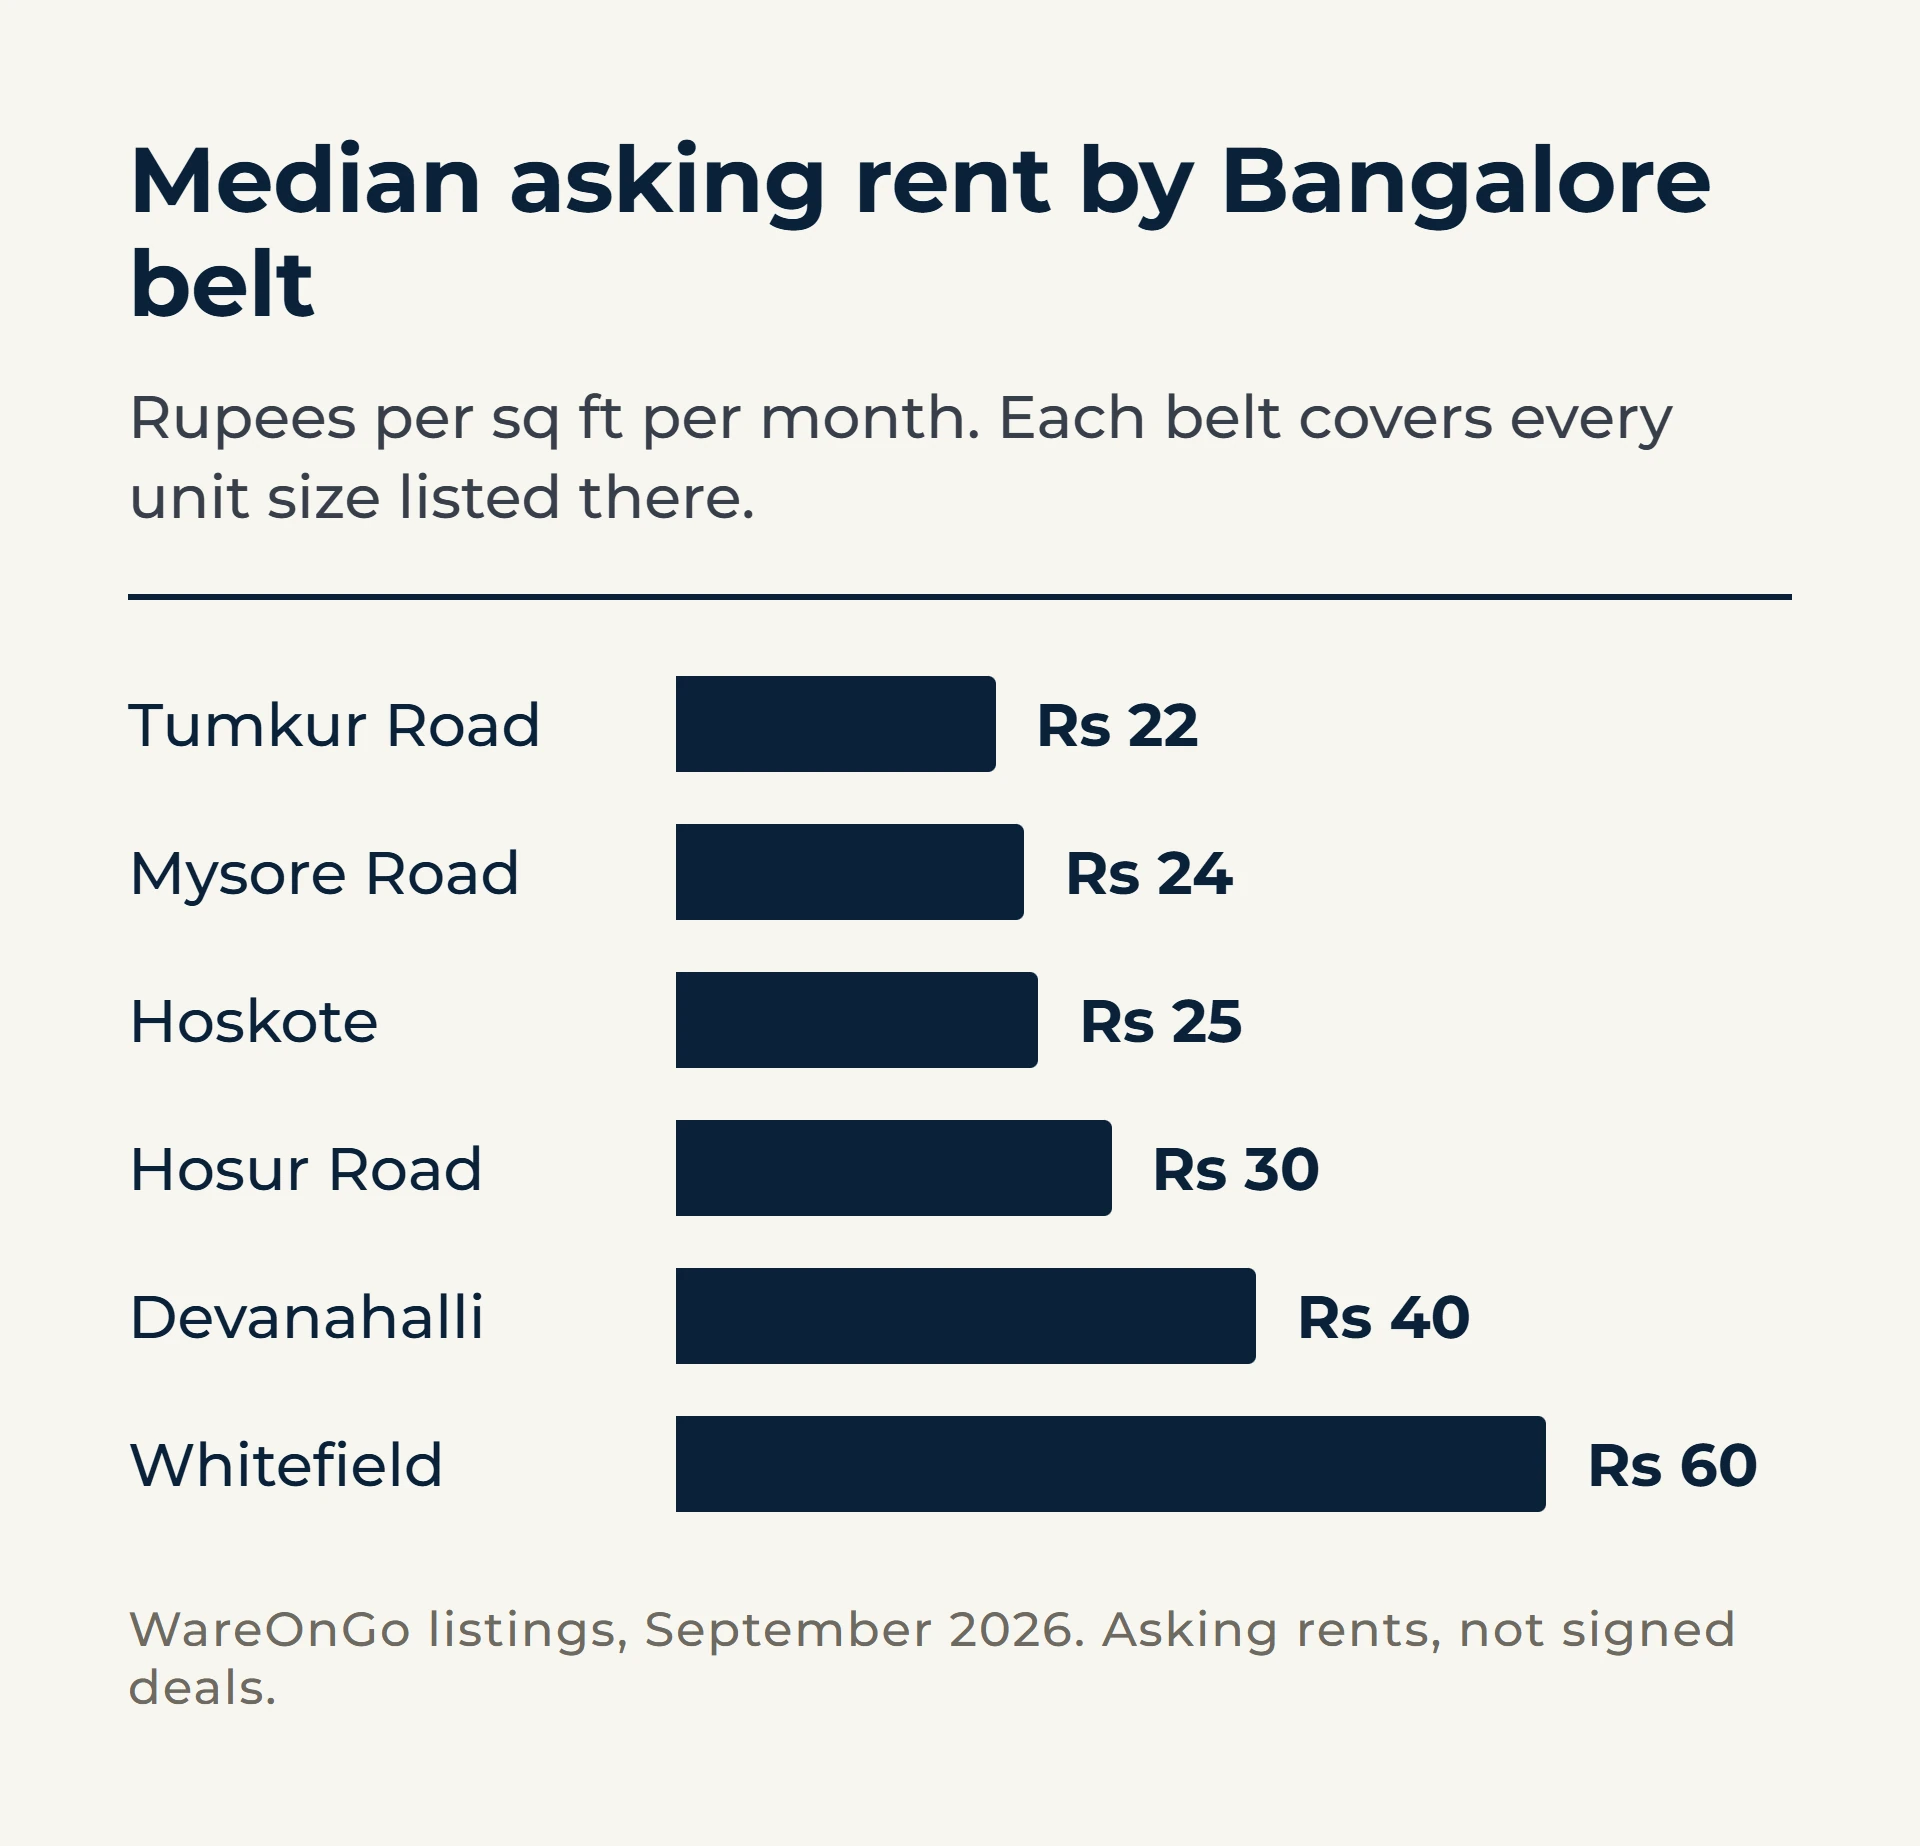
The figures below are median asking rents on warehouses listed with WareOnGo, as of September 2026. They are what owners are quoting, not signed deals, and each belt's figure covers every unit size listed there.
| Belt | Median asking rent (Rs per sq ft per month) | Median unit size | Median clear height | PEB share |
|---|---|---|---|---|
| Nelamangala / Tumkur Road | 22 | 45,000 sq ft | 35.5 ft | 94% |
| Mysore Road / NICE | 24 | 7,000 sq ft | 24 ft | 72% |
| Hoskote / Old Madras Road | 25 | 22,250 sq ft | 28 ft | 79% |
| Peenya | 29.25 | 7,000 sq ft | 13.5 ft | 20% |
| Hosur Road | 30 | 10,000 sq ft | 28 ft | 61% |
| Devanahalli / Airport | 40 | 20,000 sq ft | 25.5 ft | 60% |
| Whitefield / Sarjapur | 60 | 5,000 sq ft | 16 ft | 30% |
Unit size explains more of this table than location does:
| Unit size | Median asking rent (Rs per sq ft per month) |
|---|---|
| Under 5,000 sq ft | 62.5 |
| 5,000 to 20,000 sq ft | 30 |
| 20,000 to 50,000 sq ft | 25 |
| 50,000 to 1,00,000 sq ft | 27.25 |
| 1,00,000 sq ft and above | 25 |
What the Rents Are Telling You
At Warehouse Scale, Asking and Transacted Rents Have Converged
Our median asking rent for units above 20,000 sq ft is Rs 25. Knight Frank's average transacted rent is Rs 25.6. When what owners ask and what deals close at sit this close, there is little room left in the headline rate for large units. With 11.8% Grade A vacancy, the leverage sits in the terms around it instead: rent-free months, escalation structure, deposit size and lock-in. That is where to negotiate.
Nelamangala Is the Value Play, and It Is Getting an Upgrade
The cheapest belt per sq ft also has the tallest, newest and largest buildings. At Rs 22 and 35.5 ft of clear height, Tumkur Road gives the most pallet positions per rupee in the city. It is cheap because it has depth of supply, not because it is second-rate. The NHAI multimodal logistics park at Dabaspet, a Rs 1,770 crore, 400-acre project with Phase 1 targeted for 2026, adds an inland container depot on a side of the city that has none today. Our Dabaspet MMLP explainer covers why its phasing to 2039 matters more than its headline size.
The Airport Premium Is the Price of Time
Devanahalli quotes a median Rs 40, the highest of the outer belts, consistent with the Rs 30 to 45 Knight Frank reports for Grade A there. Occupiers pay it for proximity to air cargo and to the fast-growing north of the city, not for better buildings: the median clear height there is lower than on Tumkur Road or at Hoskote.
Inside the City, You Are Not Paying Warehouse Rates
Whitefield's Rs 60 buys a median unit of 5,000 sq ft at 16 ft of clear height, mostly RCC. That is last-mile and quick-commerce space priced off urban land values, and it should be judged against shop and commercial rents, not against a highway warehouse. Knight Frank recorded e-commerce leasing in Bangalore up 186% in 2025, which is the demand keeping these small city units expensive.
Compliant Stock Is Concentrated on the Outer Belts
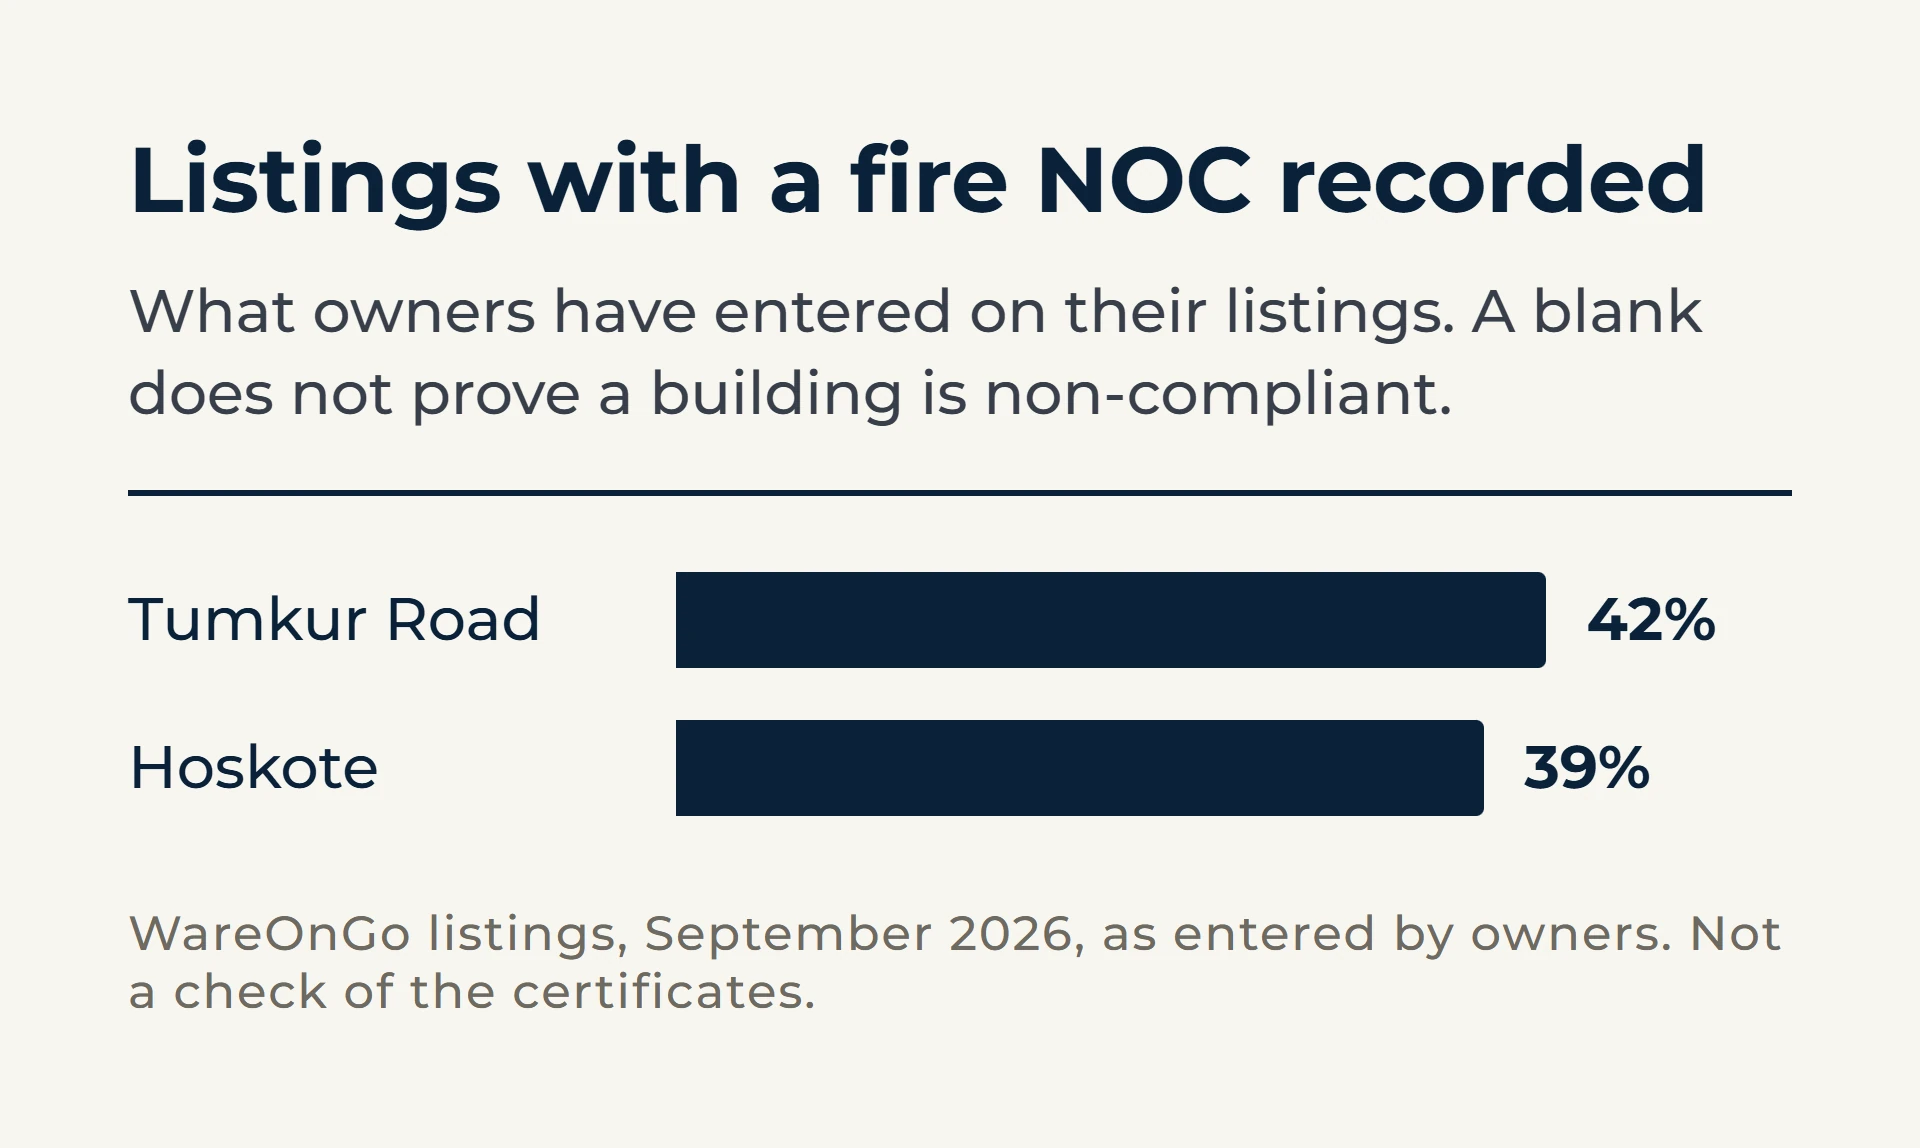
Owners recorded a fire NOC on 29 of the 69 listings on Tumkur Road and on 11 of the 28 at Hoskote, but on none of the 20 in Peenya. These are what owners have entered on our listings, not a fresh check of the certificates, and a blank does not prove a building is non-compliant. The pattern is still worth knowing: if a fire NOC is non-negotiable for you, your shortlist will lean toward the newer belts before you have looked at a single rate.
What to Watch Next
- Dabaspet's phases. Phase 1 is targeted for 2026, with later phases planned for 2034 and 2039. Rail and ICD access on NH-48 would change the maths for Mumbai-facing and EXIM occupiers first.
- Vacancy against new supply. Bangalore added 9.3 million sq ft of Grade A in 2025 against 10.8 million of demand. If supply keeps pace, rents should keep rising at around the 5% a year Knight Frank recorded, slower than in tighter markets such as Chennai, where rents rose 7%.
- The east versus northwest split. Hoskote leads on share of leasing today. A working Dabaspet terminal is the most likely thing to rebalance that.
What This Means If You Are Leasing in Bangalore in 2026
- Pick the belt by where your trucks go, not by the rate. A cheaper shed on the wrong highway costs more in line-haul every day of the lease.
- Compare rents at the same unit size. A citywide median mixes 5,000 sq ft city units with 1,00,000 sq ft highway boxes. Our guide on how to compare warehouse rent quotes shows how to reduce any quote to one comparable number.
- Negotiate the terms, not only the rate. At large sizes the headline rate is close to where deals close. Rent-free months, escalation and deposit are where 11.8% vacancy gives you room.
- Check the fire NOC and land-use papers early. They narrow the shortlist more than rent does.
Frequently Asked Questions
For warehouse-scale units of 20,000 sq ft and above, the median asking rent on WareOnGo listings is Rs 25 per sq ft per month (September 2026), close to Knight Frank's Q1 2026 transacted average of Rs 25.6. By belt, medians run from Rs 22 on Tumkur Road to Rs 40 around the airport, and around Rs 60 for small units in Whitefield.
Nelamangala and Tumkur Road, at a median asking rent of Rs 22 per sq ft per month. It is also the belt with the largest units and the highest clear heights, so it is usually the cheapest per pallet position as well as per sq ft.
By Indian standards, yes. Grade A vacancy was 11.8% at the end of 2025 (CRE Matrix with CREDAI), tied with Ahmedabad as the loosest major market. Knight Frank's all-grade figure is 19.1%. High vacancy gives tenants negotiating room on terms.
Because most Whitefield space is small RCC units inside the city, used for last-mile and quick-commerce delivery. The median unit is 5,000 sq ft and the rent reflects urban land value, so it runs at more than twice the rate of a highway warehouse.
The east. Hoskote to Narsapura took 54% of Bangalore leasing in 2025 by Knight Frank's count, and Hoskote with Soukya Road led Grade A demand at 27% by CRE Matrix's. The northwest has the most room to grow once Dabaspet's rail and container depot open. Looking for space in Bangalore? WareOnGo has 615 verified warehouses listed across the city. Tell us your size and where your trucks need to go, and we will send a matched shortlist.
Related Blogs
Looking for warehouse space?
Browse verified, physically inspected warehouses across India, or tell us your requirement and get a curated shortlist within 4 hours.